Fintech AI development · United Kingdom AI for financial services, with the controls the FCA expects.
Fintech AI development for UK banks, lenders, payment companies and wealth platforms: onboarding and KYC automation, document intelligence, risk signals and customer support assistants built with FCA and UK GDPR obligations in view.
UK-registered company. International engineering team.
01 /
Fintech AI development for UK businesses.
Financial services is where AI must be explainable, auditable and fair. Krapton builds fintech AI products for UK firms that automate the paperwork-heavy parts of onboarding, lending and servicing while keeping every decision traceable and every customer outcome fair under Consumer Duty.
From document intelligence that reads bank statements and identity documents, to assistants that resolve support queries from approved policy, to risk signals that help analysts prioritise, we design for the regulated context: model risk management, audit trails, human review and clear customer communication.
02 /
Where it earns its keep.
01 /
Onboarding and KYC documents
Extraction and checks across statements, payslips and identity documents, with exceptions routed to analysts.
02 /
Support and complaints assistants
Grounded answers from policy and product documentation, with escalation and vulnerability cues built in.
03 /
Risk and fraud signals
Pattern detection that prioritises cases for human investigation rather than deciding outcomes alone.
04 /
Operations intelligence
Summaries, reconciliations and reporting from transaction and case data for operations teams.
03 /
Built to be trusted in production.
Evaluation before release, guardrails by design and people in control of the decisions that matter.
01
Regulatory framing
Which functions are customer-affecting, which need explainability, and how Consumer Duty, SM&CR and model-risk expectations apply. Agreed with your compliance lead.
02
Data and controls design
Data lineage, access, retention, audit logging and human-in-the-loop checkpoints designed before the model is chosen.
03
Evaluate for fairness and accuracy
Test sets that include edge cases and protected characteristics analysis where relevant, with results documented for your governance.
04
Monitored deployment
Drift, quality and cost monitoring, incident procedures and periodic reviews as part of the operating model.
04 /
The decisions that shape the build.
Automated decisions with legal or similar effects on individuals engage Article 22 UK GDPR and FCA expectations on fairness and explainability. We design human review into those paths and document how the system reaches its outputs; your firm remains responsible for regulatory compliance.
What every AI engagement includes
- A use case with a measurable result and representative examples
- An evaluation set rerun on every prompt, model or data change
- UK GDPR-aware data flows, with UK or EU hosting where residency matters
- Human review and defined permissions for anything consequential
- Cost and quality monitoring after launch
05 /
Applied AI, connected to a real product.
Krapton’s own AI products, then a success story from our international portfolio describing the work delivered.
Company Signal
A clearly labelled AI brief on every newly registered UK company, for sales teams and advisers.
See the productDocuForge AI
AI that turns scanned PDFs and Word documents into structured spreadsheets.
See the productApex Engineer
An AI race engineer that gives live strategy calls while you drive.
See the productArtificial Mufti
An AI assistant that answers questions from approved sources, in a mobile app.
See the product
Sendora
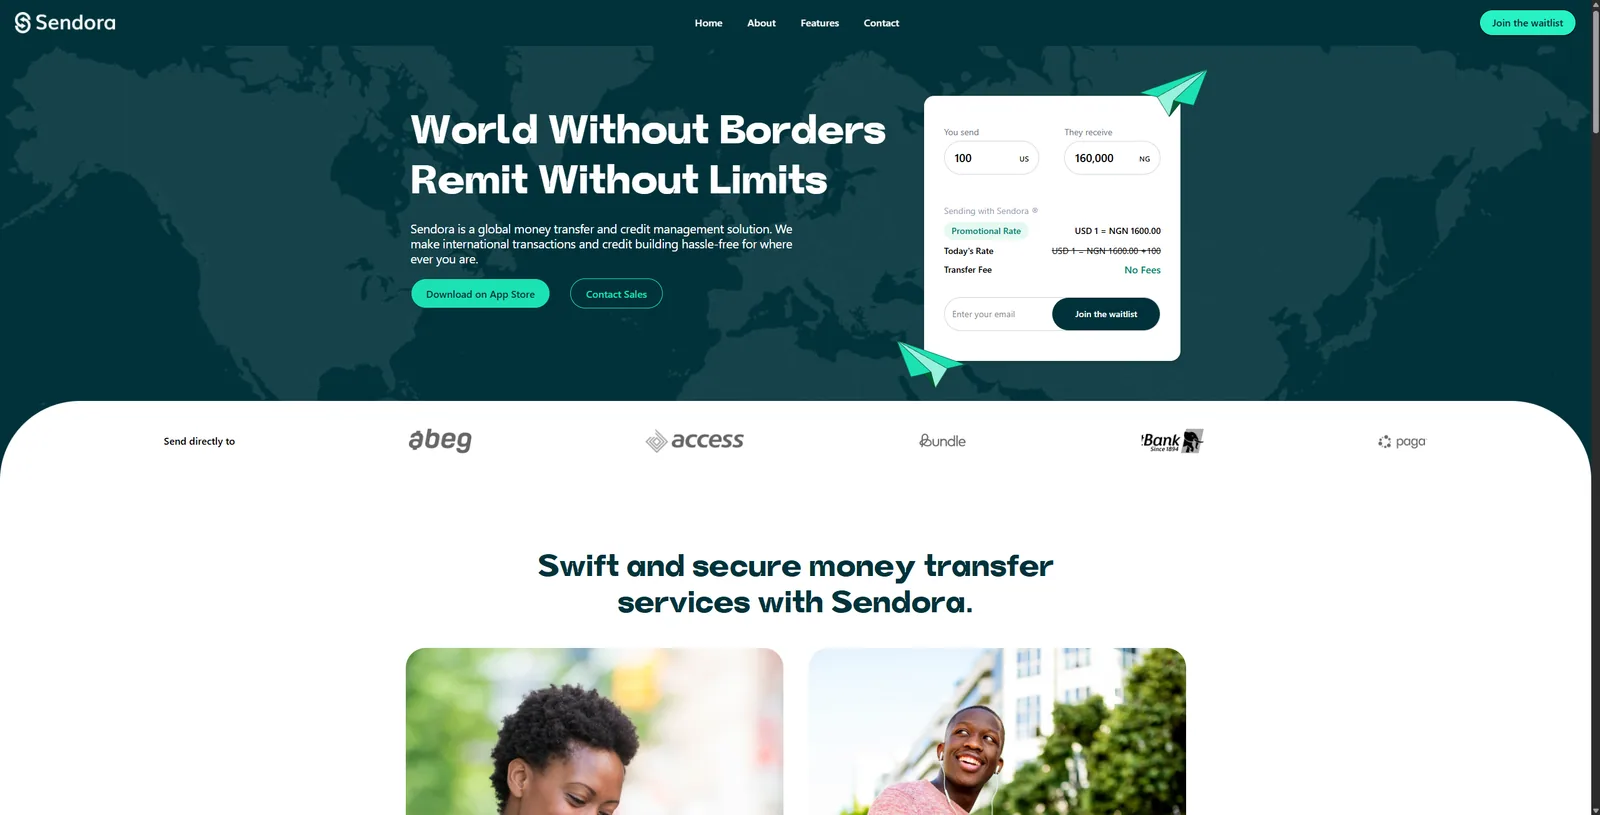
Sendora lets users send money internationally with zero transfer fees, spend on a global debit card and build credit from their phone — but the marketing site had to communicate trust, speed and global coverage at a glance, in a category where trust is everything.
Read the success story06 /
Fintech AI development: questions UK teams ask.
Can AI be used in FCA-regulated processes?
Yes, with governance: clear accountability, explainable outputs, human review of customer-affecting decisions, monitoring and records. We build to support those controls; your compliance function owns the framework.
How do you handle explainability?
Outputs carry sources, extracted evidence and confidence, and every action is logged. Where a decision needs a rationale a customer can understand, we design the interface and the record to provide one.
Where is our data processed?
In UK or EU regions on Azure, AWS or Google Cloud, with enterprise model endpoints that do not train on your data. Data flows are documented for your DPIA and supplier due diligence.
Can you integrate with our core systems?
Yes. Core banking and lending platforms, CRMs, case management, Open Banking providers and payment systems, through their APIs and secure file interfaces.
Do you have fintech experience?
Yes. Our portfolio includes Sendora, a cross-border payments platform, and blockchain gaming and ecommerce products with payment integrations. Each case study describes the work delivered.
07 /
Connect the capabilities.
Banking & fintech software
Payments, lending, wealth and regulated digital finance.
AI development
Assistants, agents, RAG search and automation built on your data.
API development
Custom APIs and integrations that connect your systems and partners.
AI MVP development
Launch a first AI product that proves demand.
Healthcare AI development
Clinical admin, triage and patient tools built with governance in mind.
Legal AI development
Contract review, document drafting and client intake for law firms.
Let’s scope your fintech AI product.
Bring the task, the examples and the systems involved. We’ll tell you what an evaluation set, a prototype and a first release would look like.