Banking & Fintech Software Development · United Kingdom Make complex financial journeys feel clear.
Fintech and banking software development for UK financial services: customer onboarding, payment and Open Banking integrations, lending and servicing platforms, operations tooling and AI, built with FCA obligations and UK GDPR in view.
UK-registered company. International engineering team.
Software for banking & fintech in the UK.
Financial products win on clarity and trust: an onboarding that does not lose people, payments that just work, statements and decisions customers can understand. Krapton builds fintech and banking software for UK firms, from payment and remittance platforms to lending journeys, wealth and savings apps, and the operations tooling behind them.
We work with Open Banking providers, payment gateways, KYC and AML services and core platforms, and we build with Consumer Duty, SM&CR accountability, operational resilience and UK GDPR in view. Our portfolio includes Sendora, a cross-border payments platform.
What gets in the way today.
Regulatory obligations everywhere
Consumer Duty, financial promotions, AML and operational resilience shape every screen and every integration.
Integration complexity
Payments, KYC, credit reference, core banking and accounting systems must work together reliably, with reconciliation.
Trust at first glance
Customers decide in seconds whether a financial product is credible, on their phone, often at night.
Software shaped around banking & fintech.
Onboarding and KYC journeys
Conversion-focused flows integrated with identity, AML and credit-reference providers.
Payments and Open Banking
Stripe, GoCardless, TrueLayer and card-scheme integrations with idempotent, reconciled processing.
Customer and operations platforms
Web and mobile apps for customers, case and operations tooling for your teams.
AI in regulated workflows
Document intelligence, support assistants and risk signals with explainability and human review.
Where software can make a difference.
Agree the regulated activities, responsible parties and data boundaries before development. Authentication, transaction state, auditability and failure recovery deserve explicit design decisions.
- Customer onboarding and account interfaces
- Payment-provider and Open Banking integrations
- Operational dashboards and reconciliation tools
- AI-assisted document checks and support
Designed with the rules in view.
The obligations that shape software in this sector. We build to support them; your compliance and legal advisers own the assessment.
Considered in every banking & fintech build
- FCA Handbook and Consumer Duty
- PSD2 and Open Banking standards
- Money Laundering Regulations 2017
- UK GDPR, including Article 22 on automated decisions
- PCI DSS for card data
- FCA operational resilience rules
Related work from our international portfolio.
Examples from Krapton’s international portfolio. Each success story describes the work delivered for that project.
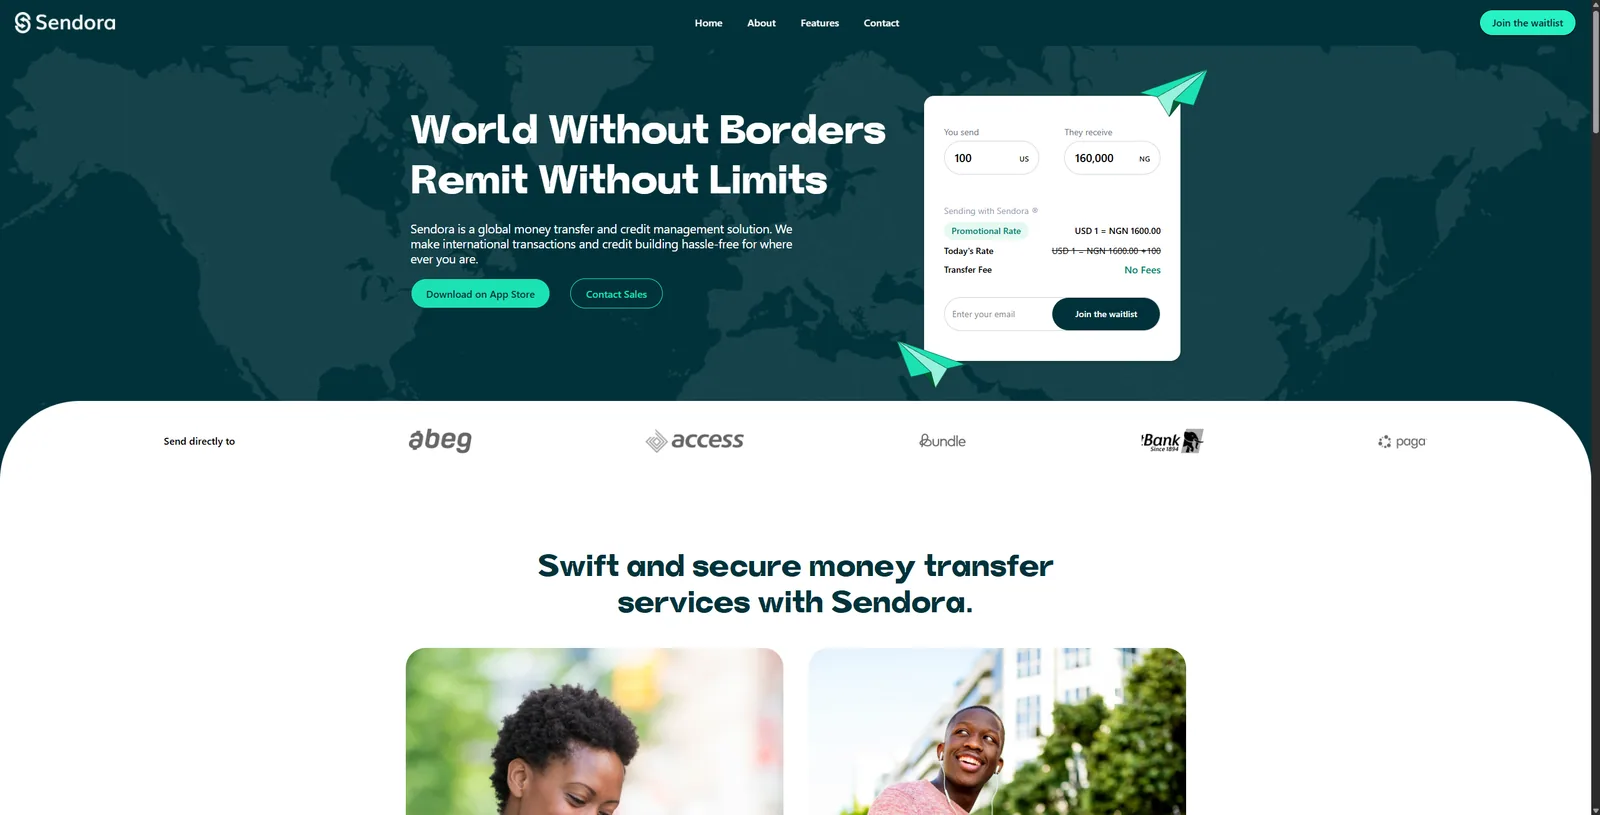
Sendora
Sendora lets users send money internationally with zero transfer fees, spend on a global debit card and build credit from their phone — but the marketing site had to communicate trust, speed and global coverage at a glance, in a category where trust is everything.
Read the success storyBanking & fintech software: questions UK teams ask.
Have you built fintech products before?
Yes. Sendora, a cross-border payments platform with multiple payout networks, is in our portfolio, alongside ecommerce and gaming products with payment integrations. Each case study describes the work delivered.
Can you integrate Open Banking and payment providers?
Yes. TrueLayer and other Open Banking providers, Stripe, GoCardless, card gateways and accounting platforms, with idempotent processing, webhooks and reconciliation built in.
How do you approach FCA requirements?
We design to support your obligations: clear customer communications, records, explainable decisions, access controls and resilience. Your compliance function owns the regulatory framework; we build the technology to fit it.
Is PCI compliance handled?
We keep card data out of your systems by using tokenised providers such as Stripe, which limits PCI scope. Where your scope is larger, we design to the applicable PCI DSS requirements with your assessor.
Can you build both the customer app and the operations tooling?
Yes, and it is usually better that way: one data model, one set of integrations and consistent controls across the customer and operations sides.
Let’s talk banking & fintech software.
Tell us what you want to improve. We’ll help you shape the right scope, team and starting point.